Taxable income is the amount PAYE rates are applied to. For an employee it is annual gross employment income minus allowable deductions and reliefs.
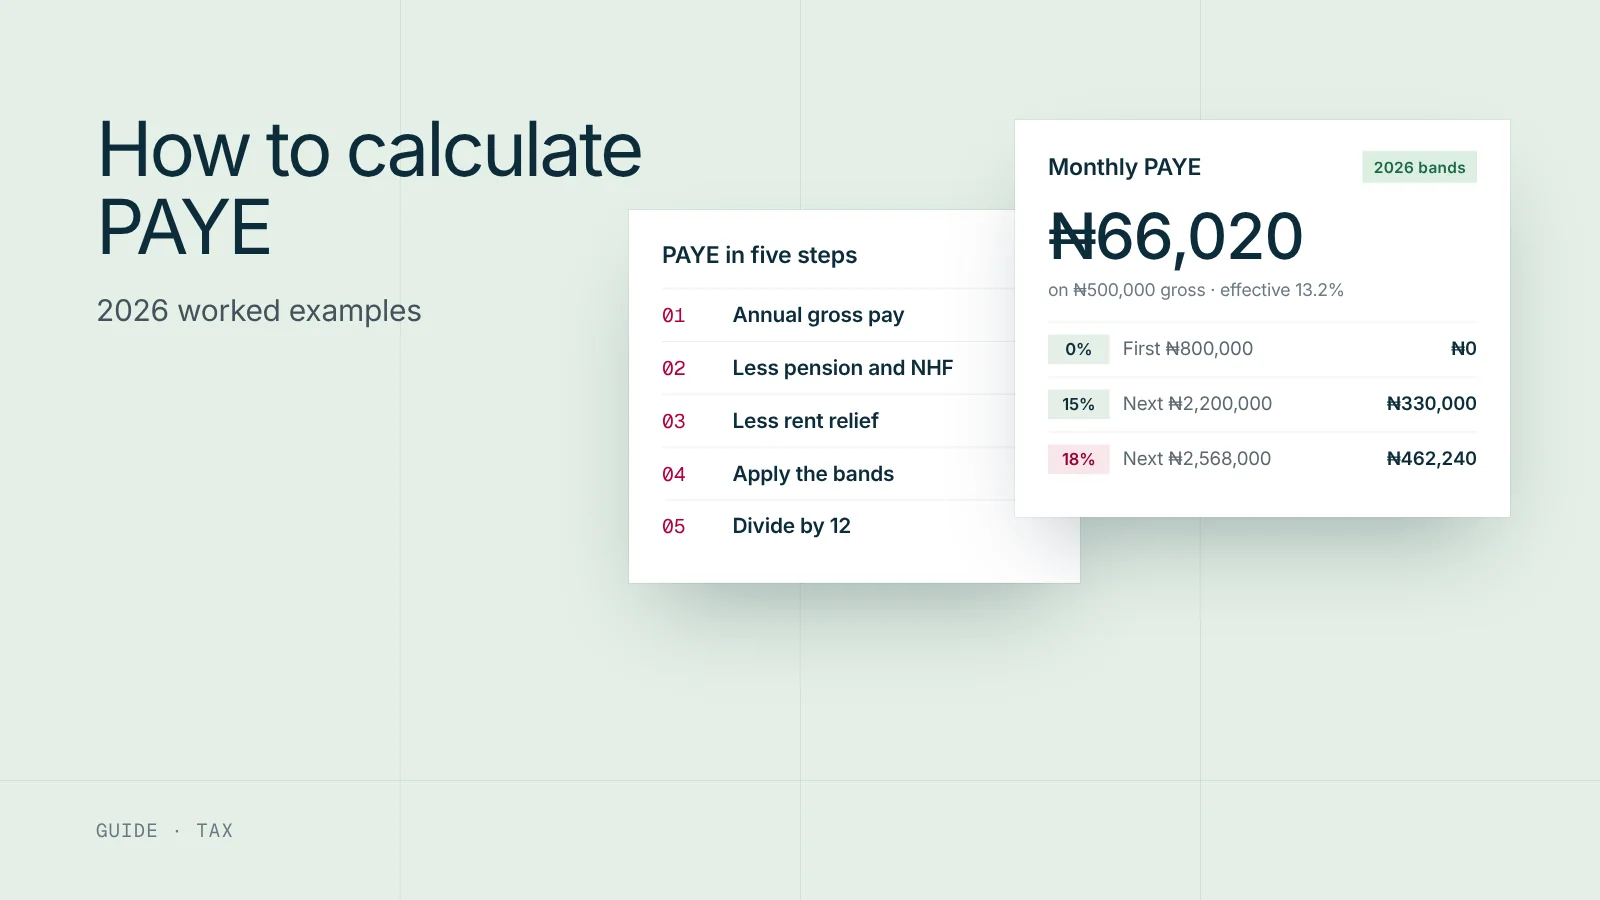
Under the Nigeria Tax Act 2025, the main deductions are the employee’s pension contribution, NHF, NHIS, life insurance premiums and mortgage interest on an owner-occupied home, plus rent relief. The 2026 bands then apply: 0% on the first ₦800,000, then 15%, 18%, 21%, 23% and 25%.
For an employee on ₦500,000 a month with the usual salary split and 8% pension, annual taxable income is ₦5,568,000. See how to calculate PAYE.
Employee management made easy
Keep employee records, attendance, leave, payroll and performance in one connected system.