Key takeaways
- The Employees' Compensation Act 2010 requires employers to contribute to the Employees' Compensation Fund managed by NSITF.
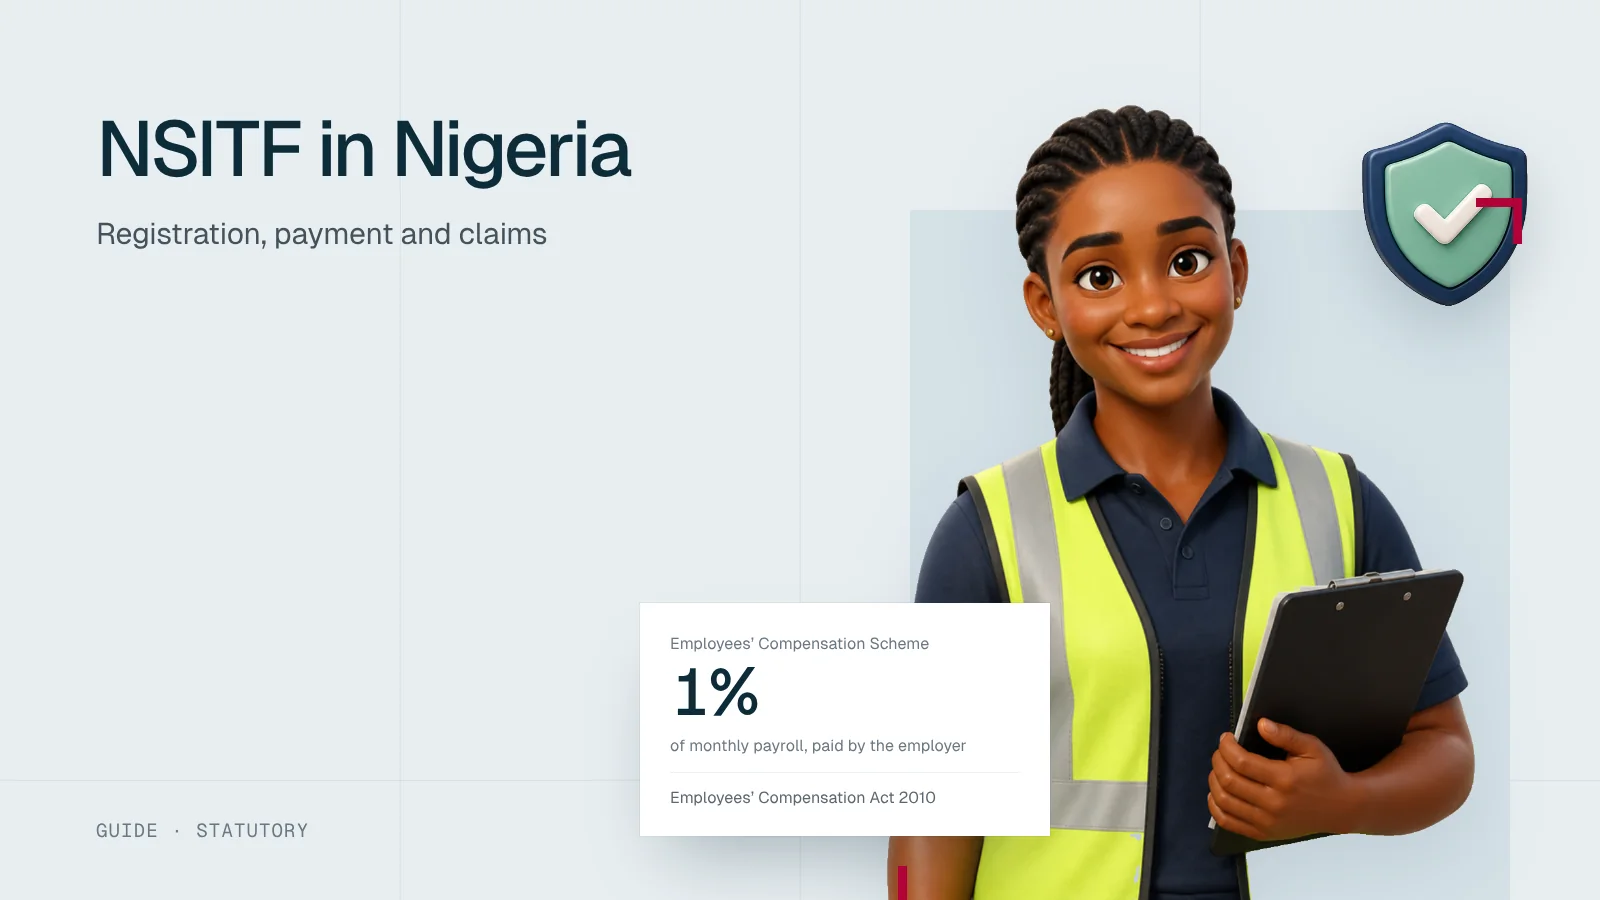
- The contribution is 1% of total monthly payroll, paid by the employer, not deducted from staff pay.
- Payment is due by the last day of each month, and statements of actual and projected payroll are due by 28 February each year.
- The scheme compensates employees for work-related injury, disease, disability and death.
The Employees’ Compensation Scheme is the least understood of Nigeria’s payroll obligations. It costs 1% of payroll, it is paid entirely by the employer, and it exists so that an employee injured at work, or the family of one who dies, is compensated without a lawsuit. The Nigeria Social Insurance Trust Fund (NSITF) runs it under the Employees’ Compensation Act 2010.
NSITF's Employees' Compensation Scheme for employers
Who must contribute
The Employees’ Compensation Act 2010 applies to employers in the public and private sectors. Every employer should register with NSITF and contribute for its employees. The scheme replaced the older Workmen’s Compensation Act regime, which relied on employers buying insurance and on employees proving their claims.
How much to pay
Section 33 of the Act sets the minimum employer contribution at 1% of total monthly payroll. NSITF can assess a different amount for an employer, so keep any assessment letter on file.
“Total monthly payroll” means the total pay of all employees for the month, not just basic salary. In practice, most employers use total gross emoluments.
| Monthly payroll | NSITF contribution (1%) | Annual cost |
|---|---|---|
| ₦1,000,000 | ₦10,000 | ₦120,000 |
| ₦5,000,000 | ₦50,000 | ₦600,000 |
| ₦20,000,000 | ₦200,000 | ₦2,400,000 |
| ₦100,000,000 | ₦1,000,000 | ₦12,000,000 |
NSITF deadlines and rates
Source: Employees' Compensation Act 2010, section 33.
What counts as payroll
Use the same total you pay staff each month before deductions: basic salary, housing, transport and every other allowance, plus overtime and bonuses paid in the month. Do not subtract PAYE, pension or NHF first; those are deductions from pay that has already been earned. If you are unsure whether an item belongs in payroll, include it and keep a note of your approach so it is applied the same way every month.
A practical check is that the NSITF figure each month should be close to 1% of the gross pay total on your payroll register. If it is far off, something has been left out.
Contract and outsourced staff
The contribution is paid by the employer of record. If you hire staff through an outsourcing firm, the firm is usually the employer and should be paying NSITF for them. Ask for evidence of its compliance when you sign the contract, because an injured worker on your premises is your problem in practice, whoever employs them. If you engage people directly on short contracts, they are your employees for NSITF purposes and belong in your payroll total.
Registration and payment
Getting compliant with NSITF
Register
Register the business with NSITF and get your employer registration details
Set up payroll
Add NSITF as an employer cost of 1% of total payroll, separate from staff deductions
Pay monthly
Pay by the last day of each month and keep every receipt
File the annual statement
Send statements of actual payroll for last year and projected payroll for this year by 28 February
Keep the certificate
Request a compliance certificate when you need one for a tender or contract
NSITF publishes its current registration and payment channels on its website. Check them before you register, as offices and online services change.
What the scheme pays for
The scheme compensates employees for:
- Injuries from accidents arising out of or in the course of employment.
- Occupational diseases caused by the work.
- Disability, temporary or permanent, resulting from those injuries or diseases.
- Death, with compensation paid to dependants.
The scheme also covers medical and rehabilitation costs. The benefit amounts and qualifying conditions are set in the Act and NSITF’s procedures, so check them with NSITF when a claim arises.
Report incidents promptly
When an employee is injured at work, record what happened, get medical care first, and notify NSITF as the Act requires. Delays make claims harder for everyone.
When an employee is injured at work
Most employers deal with a workplace injury rarely, which is why it helps to write the steps down before you need them.
- Care first. Get the employee medical attention and make the area safe.
- Record the facts. Who was injured, when, where, how it happened, who saw it, and what treatment was given. Take photographs if it helps explain what happened.
- Notify NSITF. Report the injury through NSITF’s channels as the Act requires, and keep a copy of what you sent.
- Keep the employee informed. Explain that the scheme exists and what you have done. Many employees do not know they are covered.
- Review the cause. Fix the hazard, and record what you changed.
The Act also places duties on employers to keep the workplace safe. Paying NSITF does not replace basic safety measures; it pays compensation when something goes wrong despite them.
Records to keep
- Your NSITF registration documents and any assessment letters.
- Every monthly payment receipt, matched to the month’s payroll total.
- Copies of the annual statements of actual and projected payroll.
- Compliance certificates, with their dates.
- Incident records and copies of reports to NSITF.
Keep these with your payroll records so the payroll total and the NSITF payment can always be matched.
Common mistakes
- Deducting NSITF from staff pay. The Act makes it an employer contribution, so it should never appear as a deduction on payslips.
- Using basic salary only. The base is total monthly payroll.
- Paying once a year. The contribution is monthly. Annual lump sums make reconciliation harder and can leave months unpaid.
- Forgetting the 28 February statement. It is easy to miss because it is annual.
- No proof for tenders. Request a compliance certificate early; it can take time to issue.
NSITF and private insurance
Some employers ask whether group life insurance or a group personal accident policy replaces NSITF. It does not. The Pension Reform Act 2014 separately requires employers to maintain group life insurance of at least three times each employee’s annual total emolument. NSITF contributions, group life cover and any extra insurance are separate obligations.
Why compliance matters beyond the law
Government agencies and many large companies ask suppliers for an NSITF compliance certificate before awarding contracts. Without one, you may lose a tender over a cost of 1% of payroll.
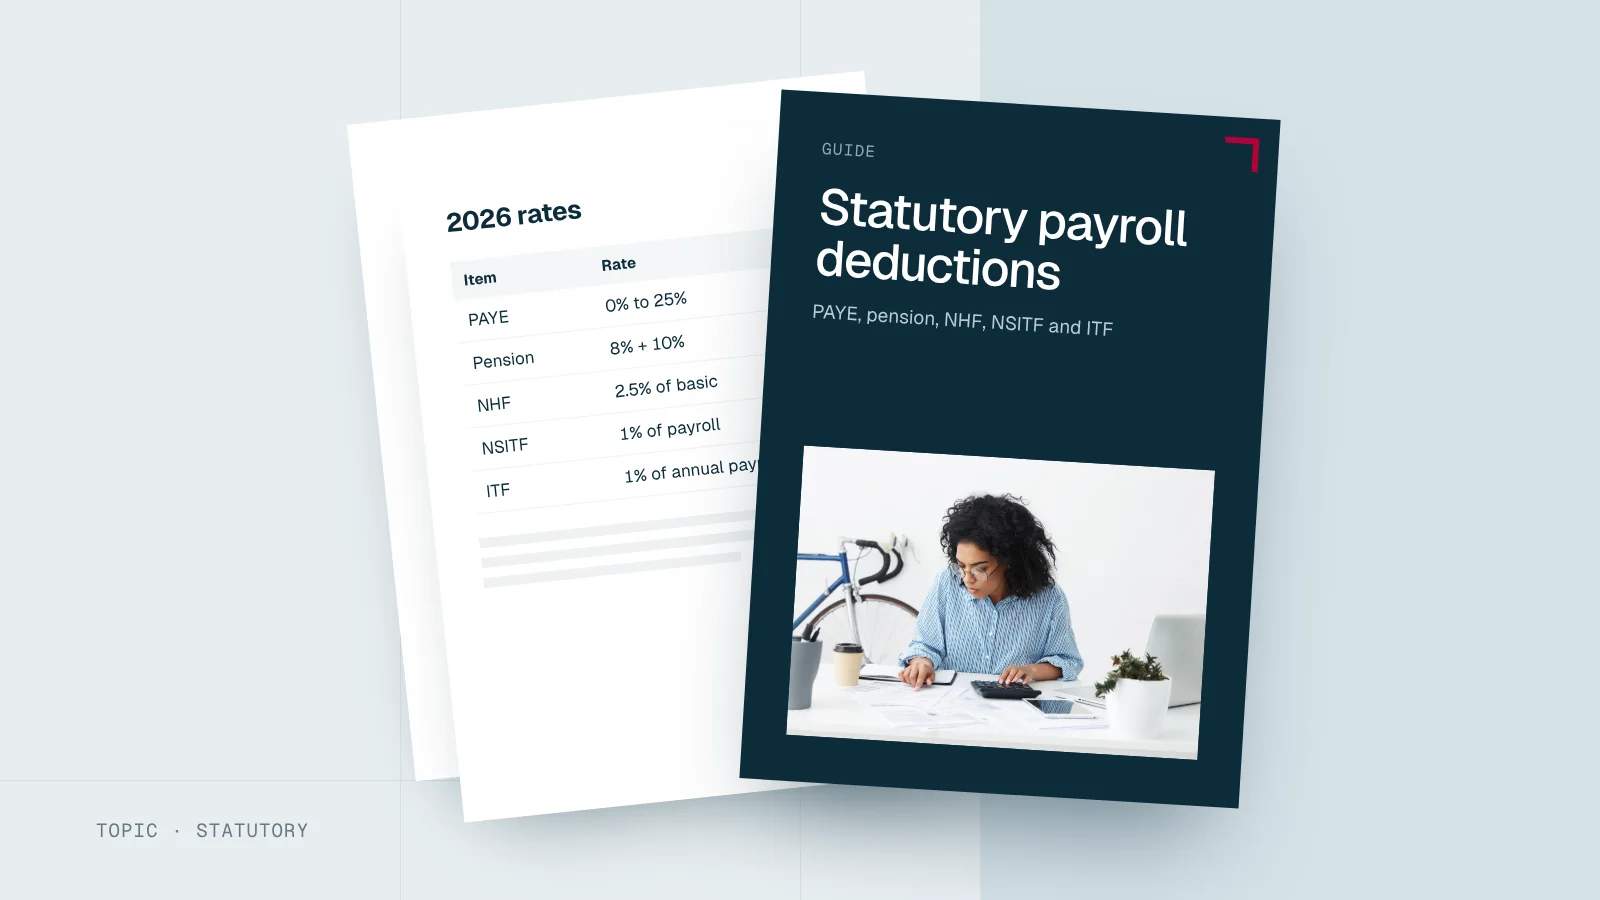
NSITF is one of five statutory items in a Nigerian payroll. Our statutory deductions guide explains the others: PAYE, pension, NHF and the ITF levy.
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Written for: Employers, accountants
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Sources
Frequently asked questions
Short answers to what employers ask us most about this topic.
What is NSITF in Nigeria?
The Nigeria Social Insurance Trust Fund. It manages the Employees' Compensation Fund under the Employees' Compensation Act 2010, which compensates employees for injuries, diseases, disability and death arising from their work.
How much is the NSITF contribution?
1% of the employer's total monthly payroll, under section 33 of the Employees' Compensation Act 2010, or the amount NSITF assesses for the employer.
Is NSITF deducted from an employee's salary?
No. It is an employer contribution. Do not show it as a deduction on payslips.
Does a small business need to register with NSITF?
The Act applies to employers generally, not only large ones. Register as soon as you take on staff, and ask NSITF about any category that might be treated differently.