Key takeaways
- Work on annual figures: annual gross pay, minus allowable deductions and rent relief, gives taxable income.
- Apply the 2026 bands to taxable income slice by slice: 0% on the first ₦800,000, then 15%, 18%, 21%, 23% and 25%.
- Divide the annual tax by 12 for monthly PAYE, and remit it to the employee's state of residence by the 10th of the next month.
- Staff earning ₦70,000 a month or less pay no PAYE.
PAYE is the income tax an employer deducts from salary each month and pays to the state tax authority. From 1 January 2026 it follows the Nigeria Tax Act 2025, which changed both the rates and the reliefs. This guide shows the method step by step and works through four salaries so you can check your own payroll. If you only need the answer for one salary, the PAYE calculator does the arithmetic for you.
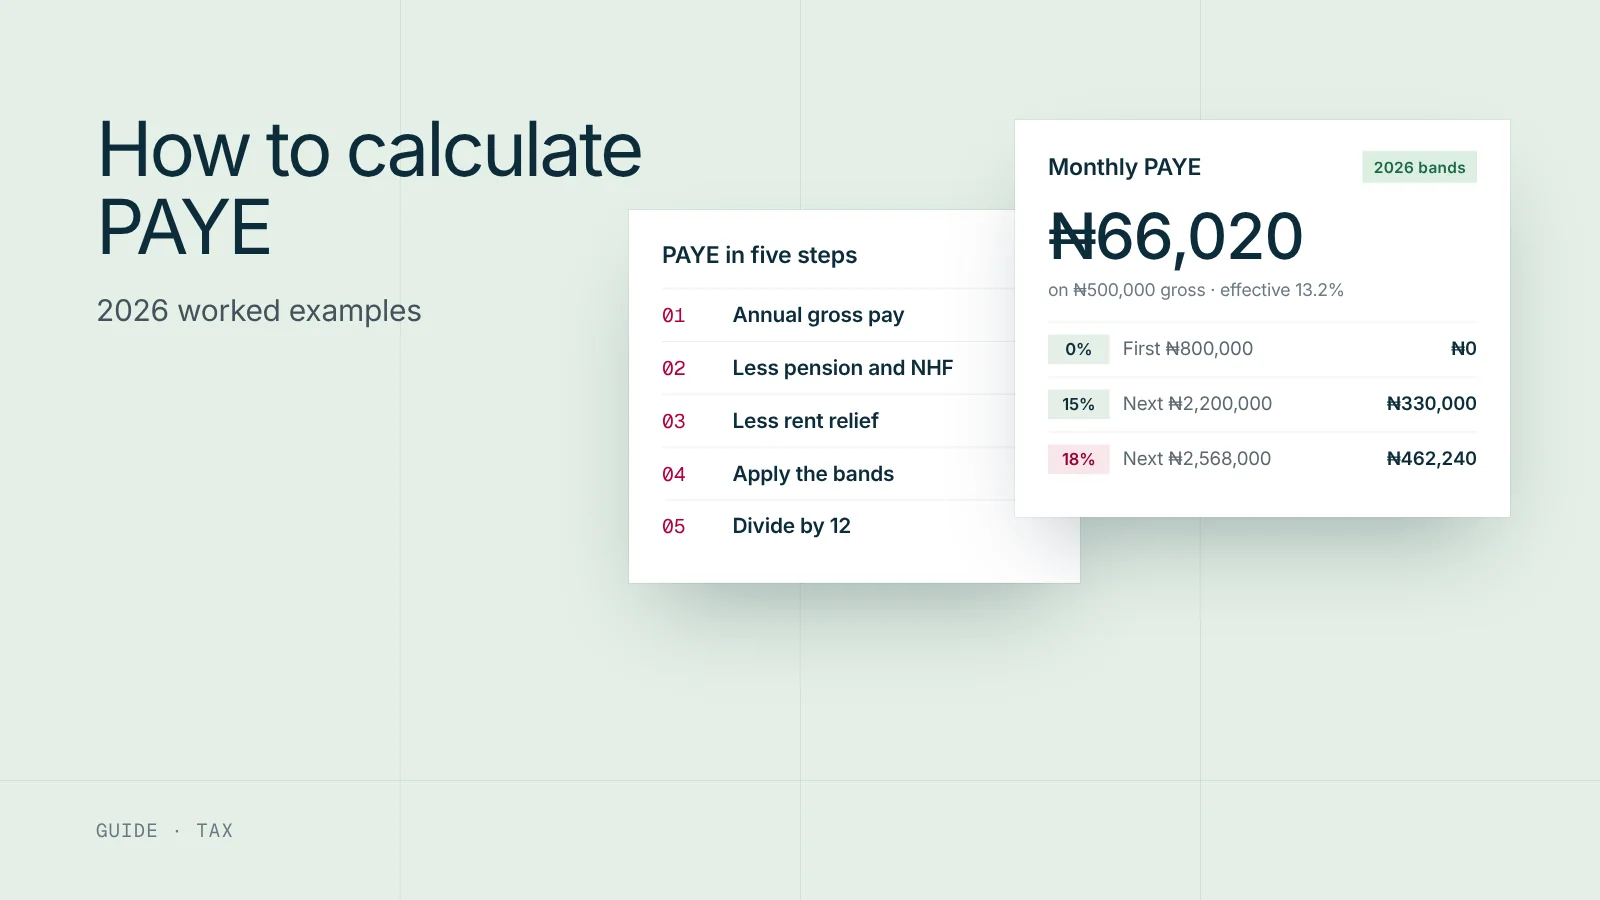
Calculating PAYE in five steps
- 01
Add up annual gross pay
Basic salary plus every allowance, for the whole year
- 02
Subtract allowable deductions
Pension, NHF, NHIS, life insurance premiums and mortgage interest on your own home
- 03
Subtract rent relief
20% of annual rent paid, up to ₦500,000
- 04
Apply the bands
0% on the first ₦800,000, then 15%, 18%, 21%, 23% and 25% on each slice
- 05
Divide by 12
That is monthly PAYE. Remit it by the 10th of the following month
Step 1: Work out annual gross pay
Add basic salary and every allowance for the year: housing, transport, utility, meal, leave allowance, 13th month and any other cash allowance. Benefits in kind, such as a company car or accommodation, are also employment income, though valuing them is outside this guide.
Most payroll teams work on monthly figures, but PAYE is an annual tax. Multiply monthly pay by 12, or add up the actual monthly figures when pay changes during the year.
Step 2: Subtract allowable deductions
The Nigeria Tax Act 2025 allows these deductions from employment income:
- The employee’s pension contribution under the Pension Reform Act 2014, usually 8% of basic, housing and transport.
- National Housing Fund contributions, 2.5% of basic salary.
- National Health Insurance contributions.
- Life insurance or annuity premiums the employee pays.
- Interest on a mortgage for the employee’s own home.
Only deduct what the employee actually pays and can evidence. The employer’s 10% pension contribution is a cost to the employer, not a deduction from the employee’s income.
Step 3: Subtract rent relief
Rent relief is 20% of the rent the employee pays for their home each year, capped at ₦500,000. It replaced the Consolidated Relief Allowance, which ended on 31 December 2025. An employee paying ₦1,200,000 a year in rent gets ₦240,000 of relief. Anyone paying ₦2,500,000 or more gets the full ₦500,000.
Employers apply rent relief through payroll only when the employee gives them the information. Decide what you will accept as evidence and keep it on file.
Step 4: Apply the tax bands
What is left after steps 2 and 3 is taxable income. Apply the bands one slice at a time:
| Slice of annual taxable income | Rate | Maximum tax in the slice |
|---|---|---|
| First ₦800,000 | 0% | ₦0 |
| Next ₦2,200,000 | 15% | ₦330,000 |
| Next ₦9,000,000 | 18% | ₦1,620,000 |
| Next ₦13,000,000 | 21% | ₦2,730,000 |
| Next ₦25,000,000 | 23% | ₦5,750,000 |
| Above ₦50,000,000 | 25% | No limit |
Drag the salary in the chart to see how each slice fills for a different salary.
How PAYE builds up slice by slice
2026 bands, with 90% of pay in basic, housing and transport and 8% pension.
Show the numbers
Source: Nigeria Tax Act 2025, Fourth Schedule (rates) and Section 30 (deductions and rent relief). Assumes basic, housing and transport make up 90% of gross, 8% employee pension on that amount, no rent relief or other reliefs. Rates effective 1 January 2026. Estimates only.
Step 5: Divide by 12 and remit
Annual tax divided by 12 is monthly PAYE. Remit it to the state tax authority where the employee lives by the 10th of the month after salaries are paid. Lagos residents’ PAYE goes to the Lagos State Internal Revenue Service, for example. Our Lagos PAYE guide covers the state process.
Worked example 1: ₦500,000 a month with rent relief
An employee earns ₦500,000 a month: ₦250,000 basic, ₦125,000 housing, ₦75,000 transport and ₦50,000 other allowances. They contribute 8% pension and pay ₦1,200,000 a year in rent.
| Step | Working | Amount |
|---|---|---|
| Annual gross pay | ₦500,000 × 12 | ₦6,000,000 |
| Pension | 8% × (₦250,000 + ₦125,000 + ₦75,000) × 12 | ₦432,000 |
| Rent relief | 20% × ₦1,200,000 | ₦240,000 |
| Taxable income | ₦6,000,000 − ₦432,000 − ₦240,000 | ₦5,328,000 |
| Tax on first ₦800,000 | 0% | ₦0 |
| Tax on next ₦2,200,000 | 15% | ₦330,000 |
| Tax on remaining ₦2,328,000 | 18% | ₦419,040 |
| Annual tax | ₦749,040 | |
| Monthly PAYE | ₦749,040 ÷ 12 | ₦62,420 |
Without rent relief the same employee would pay ₦66,020 a month. The relief saves them ₦3,600 a month.
Worked example 2: ₦150,000 a month
Same split, 8% pension, no rent relief claimed.
| Step | Amount |
|---|---|
| Annual gross pay | ₦1,800,000 |
| Pension (8% of ₦1,620,000) | ₦129,600 |
| Taxable income | ₦1,670,400 |
| Tax: 0% on ₦800,000, 15% on ₦870,400 | ₦130,560 |
| Monthly PAYE | ₦10,880 |
The effective rate is 7.3% of gross pay. Most of this employee’s income falls in the 0% and 15% bands.
Worked example 3: the minimum wage
An employee on ₦70,000 a month earns exactly the national minimum wage. Employment income at or below the minimum wage is exempt, so PAYE is nil. Pension still applies: 8% of basic, housing and transport.
Minimum wage exemption
The Nigeria Tax Act 2025 exempts employment income at or below the national minimum wage, currently ₦70,000 a month under the National Minimum Wage (Amendment) Act 2024. See our minimum wage guide.
Worked example 4: ₦5,000,000 a month
At high salaries every band is used. Taxable income after 8% pension is ₦55,680,000.
| Slice | Rate | Tax |
|---|---|---|
| ₦800,000 | 0% | ₦0 |
| ₦2,200,000 | 15% | ₦330,000 |
| ₦9,000,000 | 18% | ₦1,620,000 |
| ₦13,000,000 | 21% | ₦2,730,000 |
| ₦25,000,000 | 23% | ₦5,750,000 |
| ₦5,680,000 | 25% | ₦1,420,000 |
| Annual tax | ₦11,850,000 |
Monthly PAYE is ₦987,500, an effective rate of 19.8%.
The four examples side by side
Source: Workstat calculation, Nigeria Tax Act 2025 rates.
Situations that change the calculation
Bonuses and 13th month pay
A bonus raises annual income, so the tax on it falls in the employee’s top band. Recalculate PAYE in the month you pay it rather than spreading it evenly, unless your payroll uses a cumulative method that does this automatically.
Joiners and leavers
For staff who join mid-year, calculate tax on what they will earn from you and ask for their previous employer’s pay and tax figures for the year. For leavers, settle PAYE on their final pay, including any payment in lieu of notice or leave pay.
Pay rises and arrears
When a pay rise is backdated, the arrears are taxed when paid. Show them on a separate payslip line so the employee can see why PAYE went up that month.
Staff in more than one state
PAYE goes to the state where the employee lives, not where the office is. An employer with staff living in Lagos and Ogun remits to both state tax authorities.
Check your figures
Run each salary through the PAYE calculator and compare. If your payroll gives a different answer, check four things in order: whether pension is on basic, housing and transport; whether NHF is ticked; whether rent relief is included; and whether the old CRA is still in a formula somewhere. The last one is the most common error in spreadsheets carried over from 2025. Our guide to the new tax law for employers lists everything else that changed.
Written for: Payroll officers, accountants, HR
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Sources
Frequently asked questions
Short answers to what employers ask us most about this topic.
What is the formula for PAYE in Nigeria?
Taxable income = annual gross pay minus pension, NHF, NHIS, life insurance premiums, mortgage interest on an owner-occupied home and rent relief. Annual tax = the sum of each band's rate times the income in that band. Monthly PAYE = annual tax divided by 12.
Is PAYE calculated on basic salary or gross salary?
On gross employment income, which includes basic salary and all allowances, less the allowable deductions. Pension is worked out on basic, housing and transport, and NHF on basic alone.
How is PAYE calculated for someone who joins in the middle of the year?
Work out tax on the pay they will actually receive from you in the year, or use a cumulative method that spreads the annual tax across the remaining months. Collect details of pay and tax from any previous employer in the same year so the annual position is right.
Is a bonus taxed differently?
No separate rate applies. A bonus is part of employment income, so it raises annual taxable income and the tax on it falls in the employee's highest band. Recalculate PAYE for the month the bonus is paid.