Key takeaways
- Three items come out of the employee's pay: PAYE, the employee's pension contribution and NHF. Employer pension, NSITF and ITF are employer costs on top of salary.
- Pension is worked out on basic, housing and transport. NHF is worked out on basic salary alone. NSITF and ITF are worked out on payroll.
- PAYE is due by the 10th of the following month, pension within 7 days of paying salaries, NHF within one month, and ITF by 1 April each year.
- On a ₦500,000 monthly salary the employee's statutory deductions are about ₦102,020 and the employer pays about ₦55,000 on top.
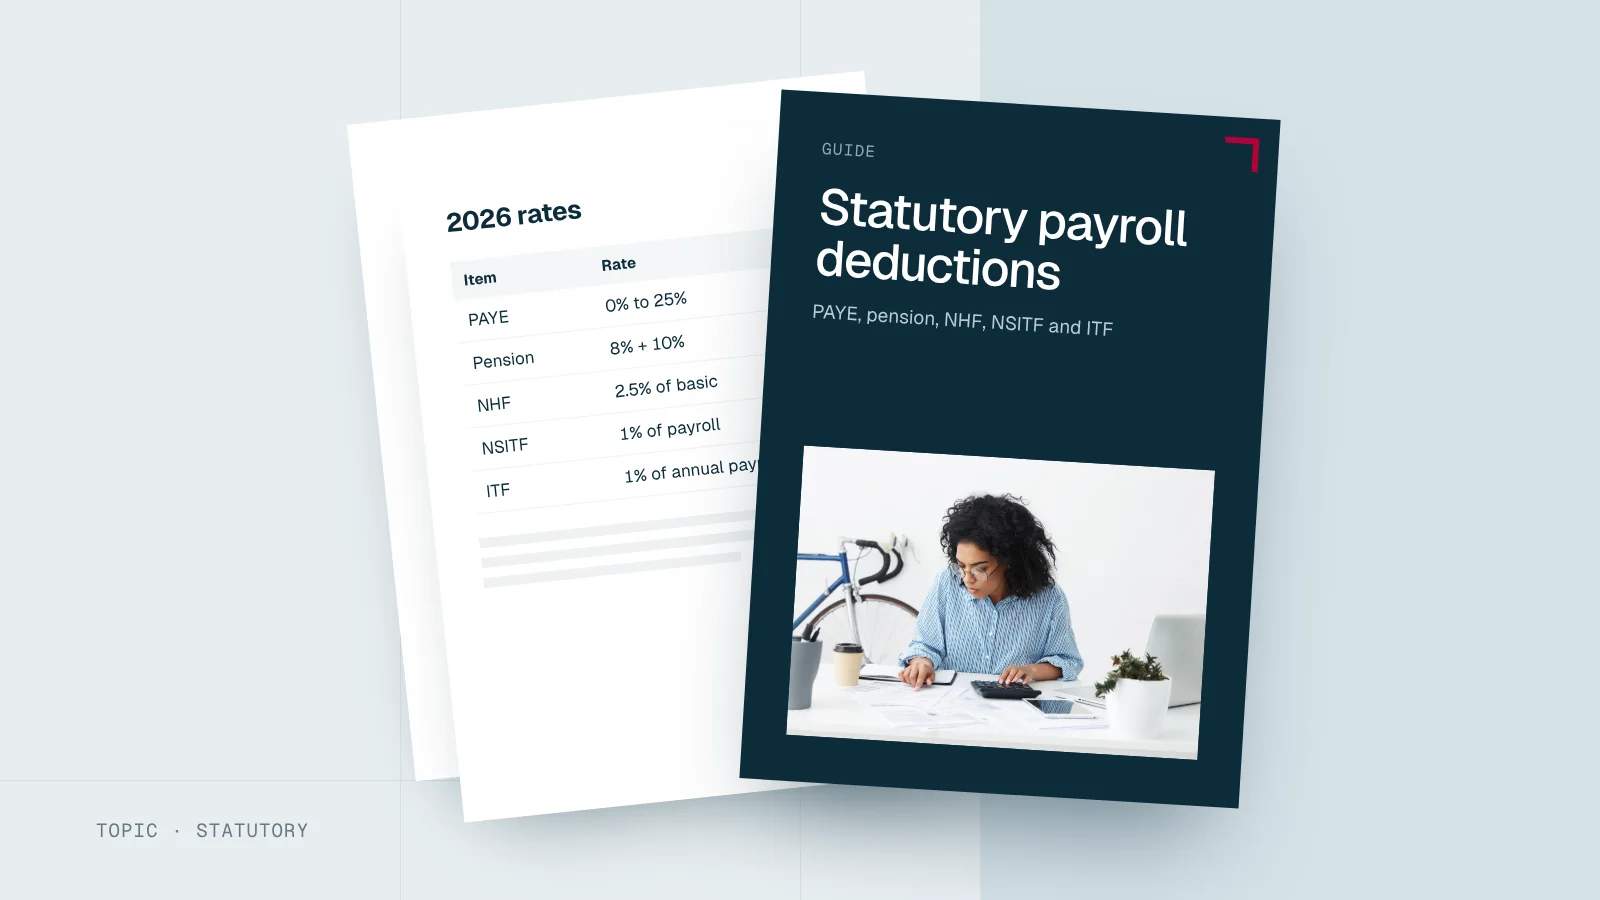
Every Nigerian payroll carries the same five statutory items: PAYE, pension, the National Housing Fund (NHF), the Nigeria Social Insurance Trust Fund (NSITF) and the Industrial Training Fund (ITF). Some come out of the employee’s pay, some are paid by the employer on top, and each has its own base, rate and deadline. This page puts them side by side and links to a full guide on each one.
The statutory items on a Nigerian payroll
Rates and deadlines that apply from 1 January 2026.
Deductions from pay and employer costs
The first question for any item is who bears it. Getting this wrong causes the most common payroll complaint: staff seeing a deduction on their payslip that the law places on the employer.
| Item | Who pays | Rate | Worked out on | Deadline | Paid to |
|---|---|---|---|---|---|
| PAYE | Employee (deducted) | 0% to 25% bands | Taxable income | 10th of the following month | State tax authority where the employee lives |
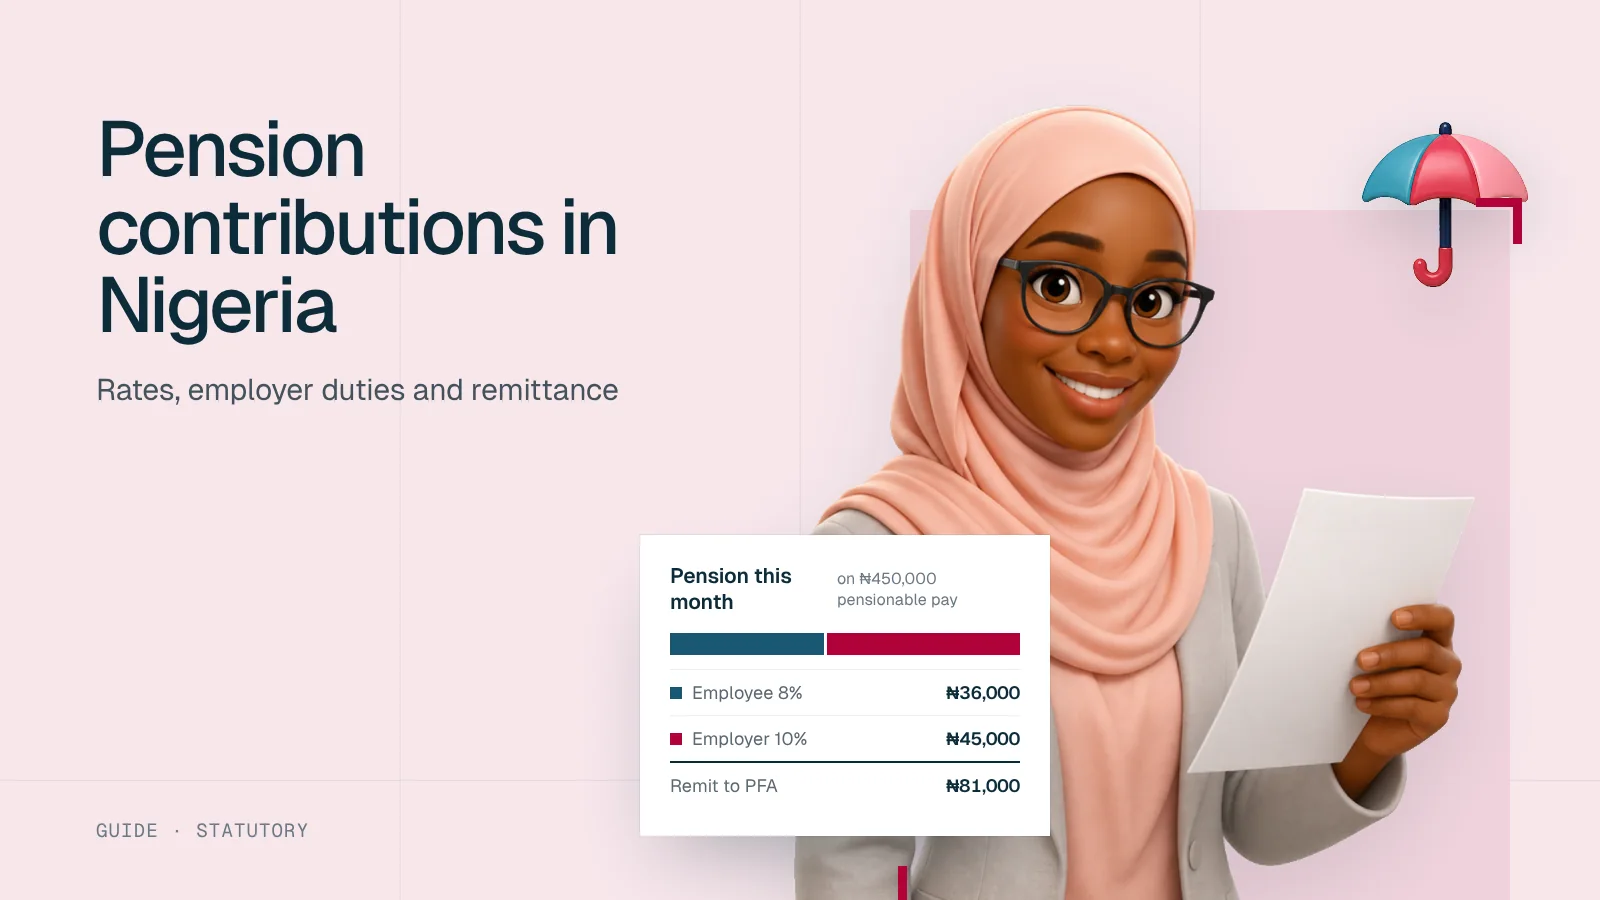
| Employee pension | Employee (deducted) | At least 8% | Basic, housing and transport | Within 7 days of paying salaries | Employee’s Pension Fund Administrator |
| Employer pension | Employer | At least 10% | Basic, housing and transport | With the employee’s 8% | Employee’s Pension Fund Administrator |
| NHF | Employee (deducted) | 2.5% | Basic salary | Within one month of the deduction | Federal Mortgage Bank of Nigeria |
| NSITF | Employer | 1% | Total monthly payroll | Monthly | NSITF |
| ITF | Employer | 1% | Total annual payroll | By 1 April for the previous year | Industrial Training Fund |
NSITF and ITF are not deductions
The Employees’ Compensation Act places the NSITF contribution on the employer, and the ITF levy is an employer contribution. Neither should appear as a deduction on a payslip.
What it adds up to on one salary
The chart shows each statutory item on a ₦500,000 monthly salary with the usual split of 50% basic, 25% housing and 15% transport, for an employee who contributes to NHF. Hover over a bar to see the amount.
Statutory items on a ₦500,000 monthly salary
Employee who contributes to NHF. ITF is shown as a monthly equivalent; it is paid once a year.
Show the numbers
| Item | Value |
|---|---|
| PAYE Deducted from pay | ₦64,895 |
| Employee pension 8%, deducted from pay | ₦36,000 |
| NHF 2.5% of basic, deducted from pay | ₦6,250 |
| Employer pension 10%, employer cost | ₦45,000 |
| NSITF 1% of payroll, employer cost | ₦5,000 |
| ITF 1% monthly equivalent, employer cost paid yearly | ₦5,000 |
Source: Workstat calculation using the Nigeria Tax Act 2025 bands and the statutory rates above.
In numbers:
| Amount | |
|---|---|
| Gross pay | ₦500,000 |
| Employee deductions: PAYE, pension and NHF | ₦107,145 |
| Net pay | ₦392,855 |
| Employer costs: pension, NSITF and ITF | ₦55,000 |
| Total cost to the employer | ₦555,000 |
Without NHF, PAYE is ₦66,020 and net pay is ₦397,980. NHF is a deduction, but it also lowers taxable income, so PAYE falls by ₦1,125 a month.
The order payroll works them out
The order matters, because pension and NHF are deducted before tax is calculated.
Working out statutory items each month
Split gross pay
Separate basic, housing, transport and other allowances.
Pension
8% employee and 10% employer, on basic, housing and transport.
NHF
2.5% of basic salary for contributing employees.
PAYE
Annual gross minus pension, NHF and other reliefs, through the 2026 bands, divided by 12.
Employer items
NSITF at 1% of the month’s payroll; set aside 1% for the annual ITF levy.
Our guide on how to calculate PAYE works through the tax step with four examples.
Each item in brief
PAYE
Income tax on employment income, deducted every month under the Nigeria Tax Act 2025 and paid to the tax authority of the state where the employee lives. Minimum wage earners are exempt. See the PAYE calculator and what changed in 2026.
Pension
The Contributory Pension Scheme under the Pension Reform Act 2014: at least 10% from the employer and 8% from the employee, paid to each employee’s Pension Fund Administrator. Employers with 15 or more staff must take part. See pension contribution in Nigeria.
National Housing Fund
2.5% of basic salary under the NHF Act, deducted from Nigerian workers and remitted to the Federal Mortgage Bank of Nigeria. See NHF deduction in Nigeria.
NSITF
The employer’s 1% contribution to the Employees’ Compensation Scheme, which compensates staff for work-related injury, disease and death. See NSITF contribution.
ITF
The Industrial Training Fund levy of 1% of annual payroll, for employers with 5 or more staff or turnover of ₦50 million or more. Up to half can be refunded if you train staff under the Fund’s schemes. See ITF contribution.
Records to keep
For every item, keep the schedule showing each employee’s figure, the payment evidence and any receipt or certificate issued. Auditors, tax authorities and pension inspectors ask for these, and they are also what employees need when a contribution is missing from their account.
Every month
Every year
When something changes
Ticks are saved in this browser only.
For the whole monthly and annual cycle in one place, see the complete payroll guide. The free payroll template calculates every item above.
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Written for: Payroll officers, accountants
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Sources
Frequently asked questions
Short answers to what employers ask us most about this topic.
What are the statutory deductions in Nigeria?
PAYE income tax, the employee's pension contribution (at least 8% of basic, housing and transport) and NHF (2.5% of basic salary). Employers also pay their own pension contribution (at least 10%), NSITF (1% of monthly payroll) and, if they qualify, ITF (1% of annual payroll).
Is NSITF deducted from the employee's salary?
No. The Employees' Compensation Act 2010 places the 1% contribution on the employer. It must not be deducted from staff pay.
Are statutory deductions taken before or after tax?
Pension and NHF contributions are deducted before PAYE is worked out, so they reduce taxable income under the Nigeria Tax Act 2025. PAYE is then calculated on what is left.