Key takeaways
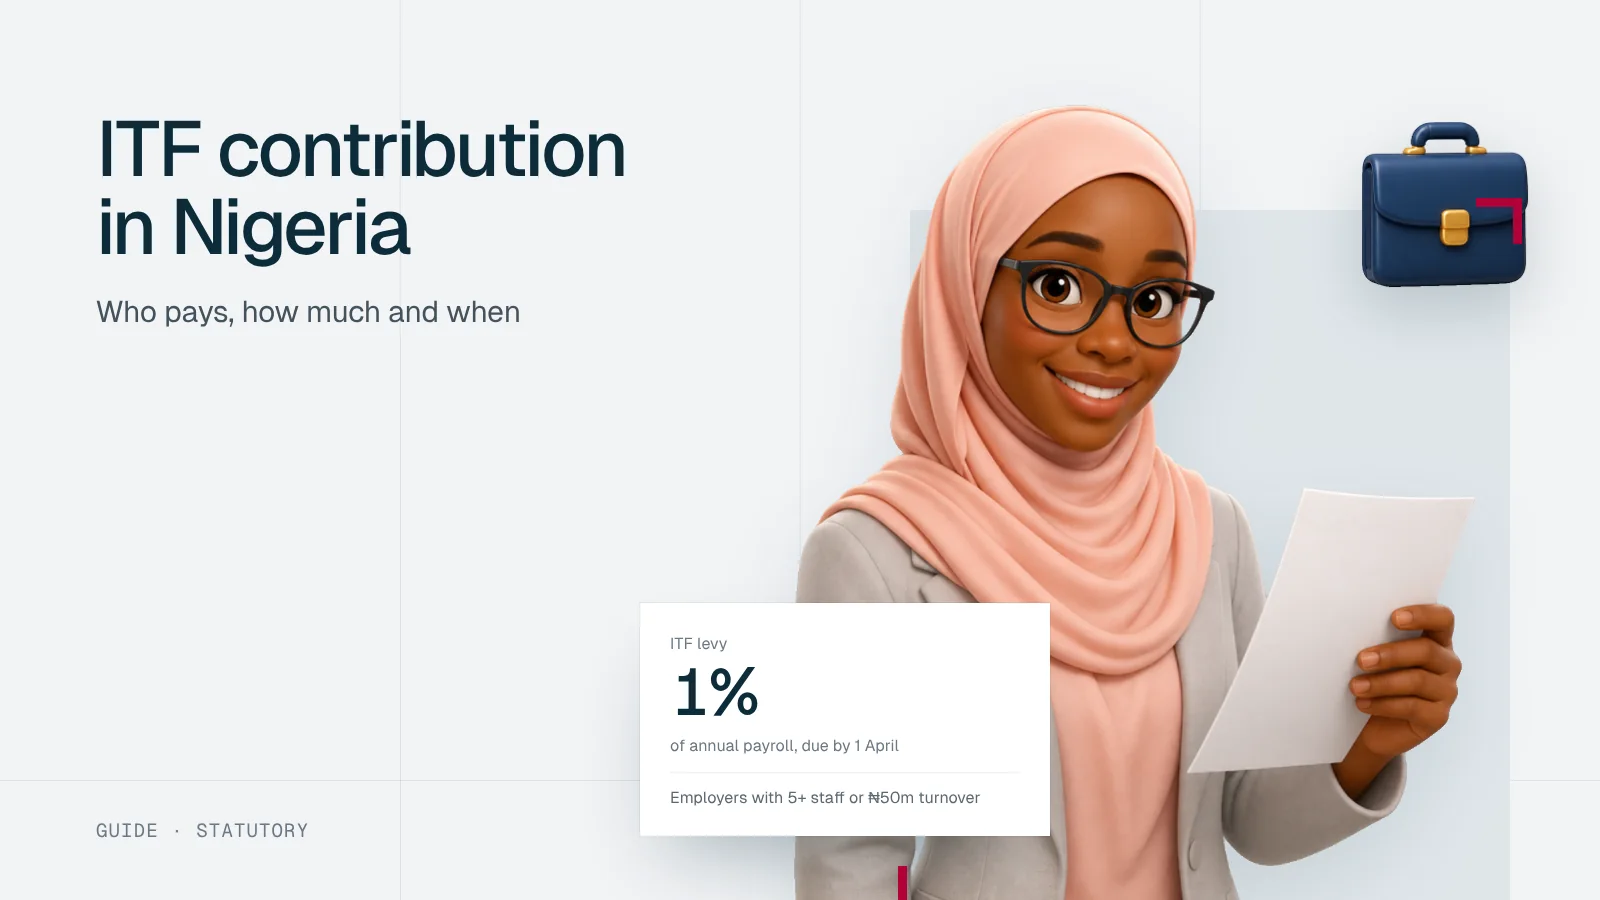
- Employers with 5 or more employees, or with turnover of ₦50 million or more a year, must pay the ITF levy.
- The levy is 1% of total annual payroll, including basic pay, allowances and other entitlements.
- It is due by 1 April for the previous year. Late payment attracts a penalty of 5% for each month or part of a month.
- Employers that train staff under the Fund's schemes can claim back up to 50% of the levy paid.
The Industrial Training Fund (ITF) levy is the statutory payroll item employers forget most often, because it is paid once a year rather than every month. It is also the only one that can be partly refunded. This guide explains who pays, how to work it out, when it is due and how to claim training costs back.
The ITF levy at a glance
What employers pay, when, and what they can claim back.
Who must pay
The ITF (Amendment) Act 2011 widened the levy. Before 2011 it applied to employers with 25 or more staff. It now covers two groups:
Employers with a “minimum of 5 employees or a turnover of N50 million and above per annum.”
ITF (Amendment) Act 2011, as summarised by Mondaq
So a firm with four employees but turnover of ₦60 million a year still pays. The test is either condition, not both.
The levy is an employer contribution. It must not be deducted from employees’ pay or shown as a deduction on payslips.
How to calculate it
The levy is 1% of total annual payroll. Payroll for this purpose covers basic pay, allowances and other entitlements paid to employees, including staff who work outside Nigeria.
| Employer | Annual payroll | ITF levy (1%) | Maximum refund (50%) |
|---|---|---|---|
| 5 staff on an average of ₦150,000 a month | ₦9,000,000 | ₦90,000 | ₦45,000 |
| 20 staff on an average of ₦300,000 a month | ₦72,000,000 | ₦720,000 | ₦360,000 |
| 4 staff on ₦150,000 a month, turnover ₦60m | ₦7,200,000 | ₦72,000 | ₦36,000 |
| 120 staff on an average of ₦400,000 a month | ₦576,000,000 | ₦5,760,000 | ₦2,880,000 |
Use gross pay, not basic salary. Working the levy out on basic alone understates it.
Set it aside monthly
Because the levy is paid once a year, set aside 1% of each month’s payroll. On a ₦6 million monthly payroll that is ₦60,000 a month, so ₦720,000 is ready by April.
When it is due
The levy for a year is due not later than 1 April of the following year. The levy on 2026 payroll is due by 1 April 2027.
Late payment attracts a penalty of 5% of the outstanding amount for each month or part of a month. On the ₦720,000 levy in the example, the penalty adds up quickly:
Late penalty on a ₦720,000 ITF levy
5% of the unpaid levy for each month or part of a month late, assuming simple monthly charging.
Show the numbers
| Item | Value |
|---|---|
| 1 month late Paid in April after the 1st | ₦36,000 |
| 3 months late Paid by early July | ₦108,000 |
| 6 months late Paid by early October | ₦216,000 |
| 12 months late Paid a year late | ₦432,000 |
Source: Workstat calculation from the ITF (Amendment) Act 2011 penalty rate.
A year’s delay costs more than half the levy itself. The Fund can also sue to recover unpaid contributions, underpayments and penalties.
Claiming back up to 50%
The levy is meant to pay for training. Employers that train their staff in line with the Fund’s reimbursement schemes can claim back part of what they paid. The 2011 amendment cut the maximum refund from 60% to 50% of the amount paid.
From levy to refund
Register
Register the business with the ITF, which records your staff numbers and payroll.
Pay on time
Pay 1% of the previous year’s payroll by 1 April.
Train and document
Run training that meets the Fund’s scheme rules, and keep records of who was trained, on what and at what cost.
File the returns
Submit the returns and evidence the Fund asks for, accurately. False returns are an offence.
Claim
Apply for reimbursement, up to 50% of the levy paid.
The requirements for training to qualify are set by the Fund and change from time to time. Check the current scheme rules with the ITF before you plan a training budget around a refund.
Other duties and offences
The Act also expects employers to train staff adequately and to accept students for industrial attachment. Failing to do so, or making false returns, is an offence with fines that rose sharply in 2011.
| Who | First breach | Each later breach |
|---|---|---|
| Company | ₦500,000 | ₦1,000,000 |
| Chief executive, secretary or principal officer | ₦50,000 or two years’ imprisonment | Two years’ imprisonment without the option of a fine |
These offences sit apart from the late-payment penalty, which applies to any unpaid levy.
Where ITF fits in payroll
The ITF levy is one of three employer costs on top of salary, alongside the employer’s 10% pension and the 1% NSITF contribution. Unlike the other two, it is paid once a year on the whole year’s payroll. See statutory payroll deductions for all five items side by side, and NSITF contribution for the monthly 1% that is easily confused with ITF.
ITF checklist
Check
Every month
Every year
Ticks are saved in this browser only.
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Written for: Employers, accountants
Run payroll with Paystat
Process payroll with structured, consistent calculations and a full history of every pay cycle.
Sources
Frequently asked questions
Short answers to what employers ask us most about this topic.
Who pays ITF in Nigeria?
Employers with at least 5 employees, or with fewer staff but turnover of ₦50 million or more a year, under the Industrial Training Fund (Amendment) Act 2011. The levy is an employer cost and is not deducted from staff pay.
How is the ITF levy calculated?
1% of total annual payroll. Payroll includes basic pay, allowances and other entitlements paid to employees, whether they work in Nigeria or outside it. On an annual payroll of ₦72 million, the levy is ₦720,000.
Can ITF be refunded?
Up to 50% of the levy paid can be reimbursed when the employer trains staff in line with the Fund's reimbursement schemes. Check the current requirements with the ITF before you plan training around a claim.